
United States: Reshoring, the Robot Boom and Cable Import Gaps
Quick Answer: The United States installed a record 38,500 industrial robots in 2025, passing Japan into second place, and reshoring economics keep pushing demand for imported motion cable upward.
For years, the American automation story was a story of intentions: reshoring announced, factories promised, robots projected. IFR’s World Robotics 2026, published in September 2026, finally put a hard number under the promises. The United States installed about 38,500 industrial robots in 2025, twelve per cent more than the year before, and for the first time moved ahead of Japan into second place among national markets. Behind that record sits a policy and economic environment that keeps pushing the same direction, and behind the robots sits a cable demand that the American cable industry, for reasons this article explains, cannot fully supply on its own.
Introduction
Three forces converged to produce the 38,500-unit year. Labour markets in manufacturing stayed tight enough that vacancy rates in production roles remained a persistent complaint across industries. Semiconductor, battery and EV plants funded by national incentives moved from drawings to construction, and their production lines absorb robots at a pace conventional plants do not. And the cost curve of automation itself kept falling, as machine vision and AI tooling made robots usable for jobs that previously needed a systems engineer on standby. None of these forces looks temporary, which is why the market’s growth reads as structural rather than cyclical.
This article reads the American market from the demand side: where the robots are going, what they consume in cable, and why imports fill the gap. The certification path for cable and machines entering the United States, including UL recognition, is covered in its own guide and is only touched on here. Buyers comparing overseas cable sources should start with the framework in the guide to international sourcing mistakes.
Reshoring Is Not One Story, It Is Several
The word reshoring covers four distinct demand streams, and they buy cable differently. Semiconductor fabs and their construction waves consume cleanroom-rated motion cable and the drag chains that move wafers and carriers. Battery and EV plants, clustered around announced gigafactory projects, consume oil- and coolant-resistant flex cable at volumes the industry has not seen before. General manufacturing reshoring, driven by tariff exposure and supply-chain risk, adds machine-tending and material-handling robots across mid-sized plants. And warehouse automation, the quietest of the four, consumes more continuous-motion cable than all the others combined, spread across fulfilment centres that never stop moving.
The four streams also share a timing pattern: they scale faster than the domestic supply base does. Building cable production capacity takes years, while robot installations arrive on the schedules of construction projects and expansion capital. That gap is the import story, and it is structural rather than temporary. A plant commissioned in 2026 does not care where its flex cable was extruded; it cares whether the flex-life evidence holds at the duty the machine actually runs.
What the American Fleet Buys
American automation demand skews toward certain cable profiles. Machine tending and material handling, the workhorse applications, put drag chains and dress packs under three-shift duty with wide ambient swings, favouring PUR-jacketed constructions with generous abrasion margins. Warehouse and fulfilment automation consumes continuous-motion cable for shuttles, lifts and charging interfaces, with cycle counts that make flex-life evidence the first question buyers ask. Automotive, still the largest single robot-using industry, adds weld-adjacent torsion and spatter duty. And the semiconductor segment, though smaller in unit count, specifies at the strictest level of any cable market in the world, because a down tool costs more per hour than most factories earn in a week.
The failure patterns behind those requirements are consistent with any mature market, and the guide to why cables fail on machines maps them: premature flex failure at tight radii, shield breakdown near drives, jacket swelling in coolant. American buyers increasingly specify against those modes directly, asking for test conditions rather than ratings, a purchasing culture the country imported along with its European and Japanese machine tools.
| Demand stream | Scale driver | Cable profile | Buyer's first question |
|---|---|---|---|
| Semiconductor fabs | Nationally funded fab construction moving into production | Cleanroom-rated motion cable, drag chains for wafer handling, strict EMI control | Particle and outgassing behaviour, flex evidence |
| Battery and EV plants | Gigafactory projects entering production across several states | Coolant- and oil-resistant flex cable, fast indexing gantries, long runs | Chemical resistance data and batch consistency |
| General reshoring | Tariff exposure and supply-chain risk pushing mid-market automation | Machine-tending drag chain, dress packs, wide ambient range | Honest flex-life rating at the real radius |
| Warehouse automation | E-commerce fulfilment expansion, round-the-clock duty | Continuous-motion cable, charging interfaces, highest cycle counts | Cycle evidence and spares availability |
The Import Gap and How It Gets Filled
The table’s last column hints at the market’s character: American buyers are practical and documentation-aware, but they are also exposed. Integrators commissioning lines under schedule pressure need cable that arrives when promised, with the papers the authority having jurisdiction and the insurance carrier will ask about. Where domestic supply cannot meet volume, the burden of proving an imported cable falls on the importer, which is why the comparison between supply models in the guide to OEM and ODM sourcing matters as much as the cable’s test data.
When Reshoring Headlines Are Not the Answer
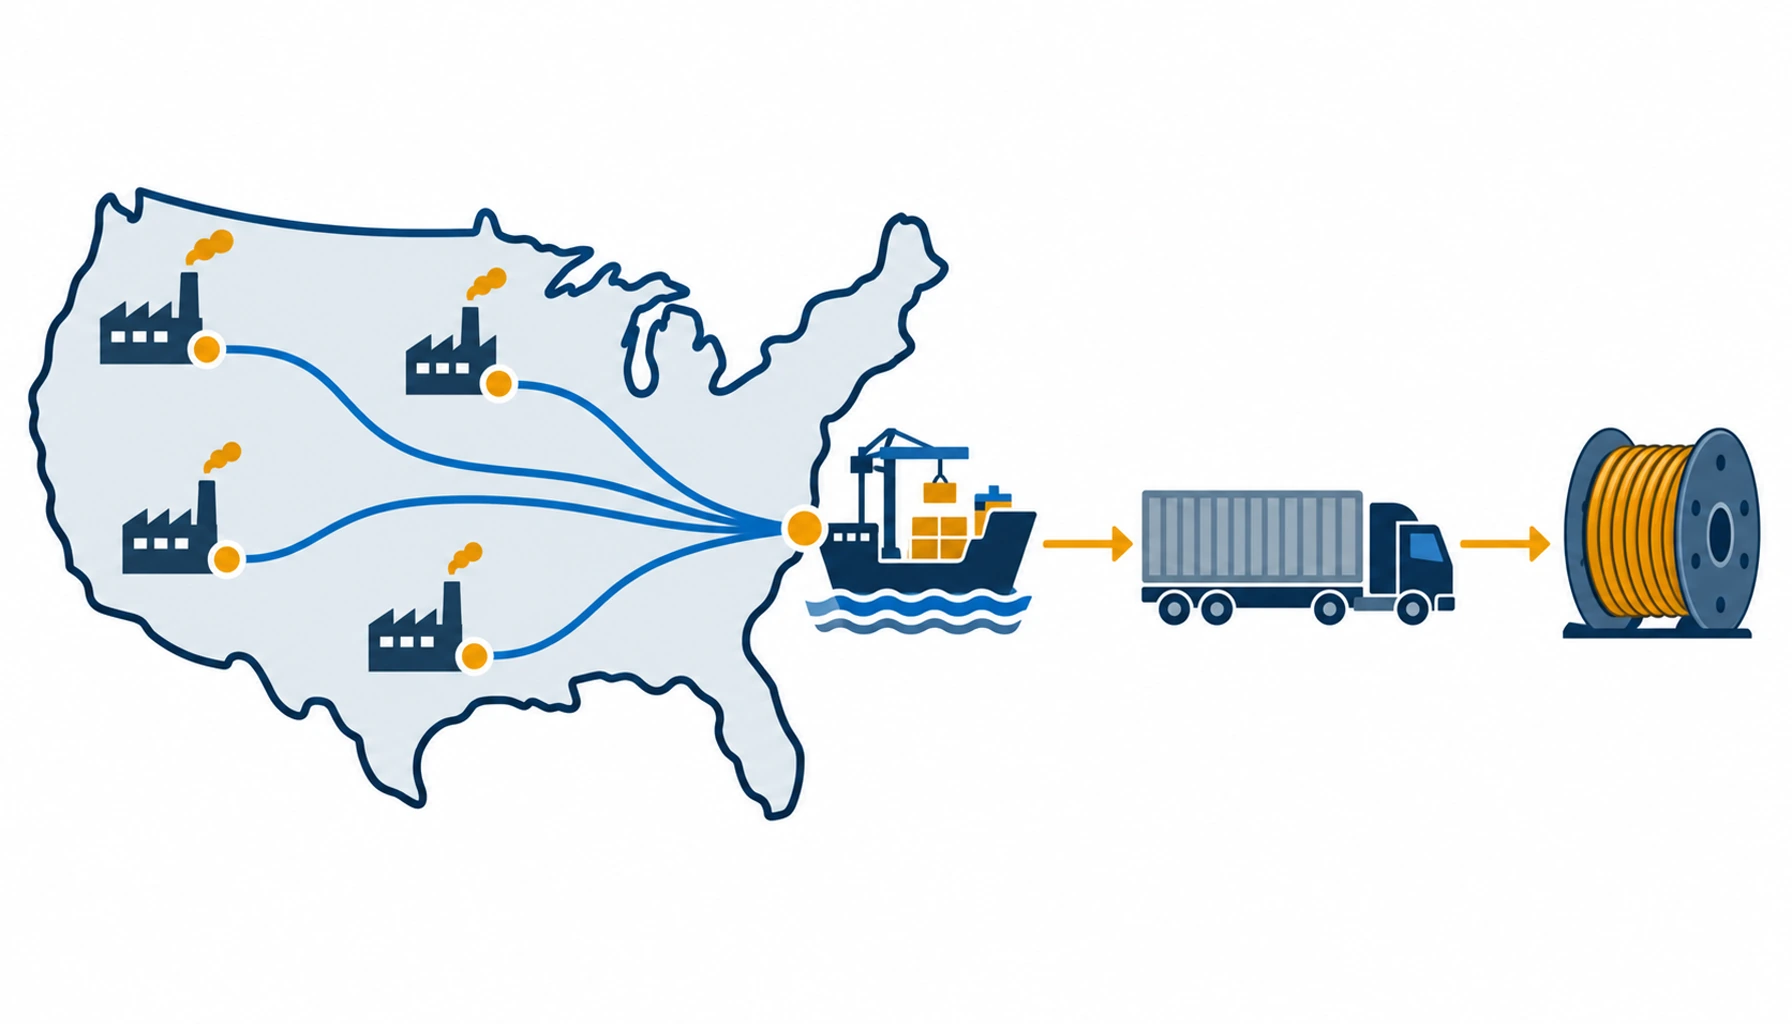
The American cable industry is strong in power, utility and construction product, but high-flex motion cable is a different business. It depends on ultra-fine stranding, short-lay twisting equipment and flex test rigs, a production base concentrated in Europe and Asia. The consequence is simple arithmetic: as American robot installations set records, the majority of flex-rated cable inside them arrives by sea. Importers and integrators manage that flow, and their recurring problems are predictable: long lead times for specialty constructions, minimum order quantities that dwarf a single machine’s need, and documentation that arrives incomplete for the American compliance conversation.
Each problem has a sourcing answer. Lead time risk shrinks when projects order specialty cable at design stage rather than at installation. Minimum order pressure eases through suppliers who hold popular constructions in semi-finished form or who split production runs. Documentation gaps close when the purchase order names the certificates and test evidence required, rather than discovering the requirement at the dock. The wider risk catalogue around cross-border equipment buying is collected in the analysis of international sourcing mistakes, and the infrastructure side of American factory projects, from service entrances to distribution, follows the logic in the industrial power distribution checklist.
| Decision | Why it matters in the US flow | Practical handling |
|---|---|---|
| Order timing | Specialty flex cable made to order carries weeks of production lead time | Specify at design stage; hold spares for critical axes |
| Certificate scope | North American practice expects recognised component approval on flexible cordage | Name the required evidence in the purchase order, including who holds it |
| Order size versus MOQ | One machine rarely fills a production run | Use suppliers with semi-finished stock or split-run flexibility |
| Freight and customs | Copper weight makes freight cost real and schedules weather-sensitive | Plan the landed-cost model, not the ex-works price |
| Armour and protection choice | Runs between buildings or under floors may need protected constructions | Decide per run using the reasoning in the armoured versus unarmoured guide |
RFQ Checklist: Motion Cable for a US Automation Project
Three cautions. First, record installations do not guarantee a record for any one supplier segment; the growth lands unevenly across industries, and a cable supplier targeting battery plants faces different timing than one targeting warehouses. Second, the import gap is a volume statement, not a quality verdict on domestic production; for standard constructions, domestic supply works well, and the gap is specifically in high-flex specialty product. Third, policy tailwinds do not exempt a project from its own diligence: the cable still has to suit the duty, the certificates still have to match the market, and the certification overview in the cable certification checklist remains the honest starting point for that conversation.
Conclusion
Send these with the inquiry so the quote survives contact with the project schedule:
- Application class: fab, gigafactory, general machine tending or warehouse duty
- Duty per axis: travel, cycles per shift, ambient range including cold docks or hot roofs
- Actual bend radius and carrier type, with flex evidence requested at that radius
- Environmental exposure: coolant, oil, washdown, chip strike or cleanroom class
- Required North American compliance evidence, named in the order rather than assumed
- Delivery window with the project schedule attached, so production can be planned
- Spares strategy for critical axes, agreed before commissioning
- Landed-cost terms: who handles freight, customs and inland delivery


