Bid Bonds and Performance Guarantees in Central Asian Cable Contracts
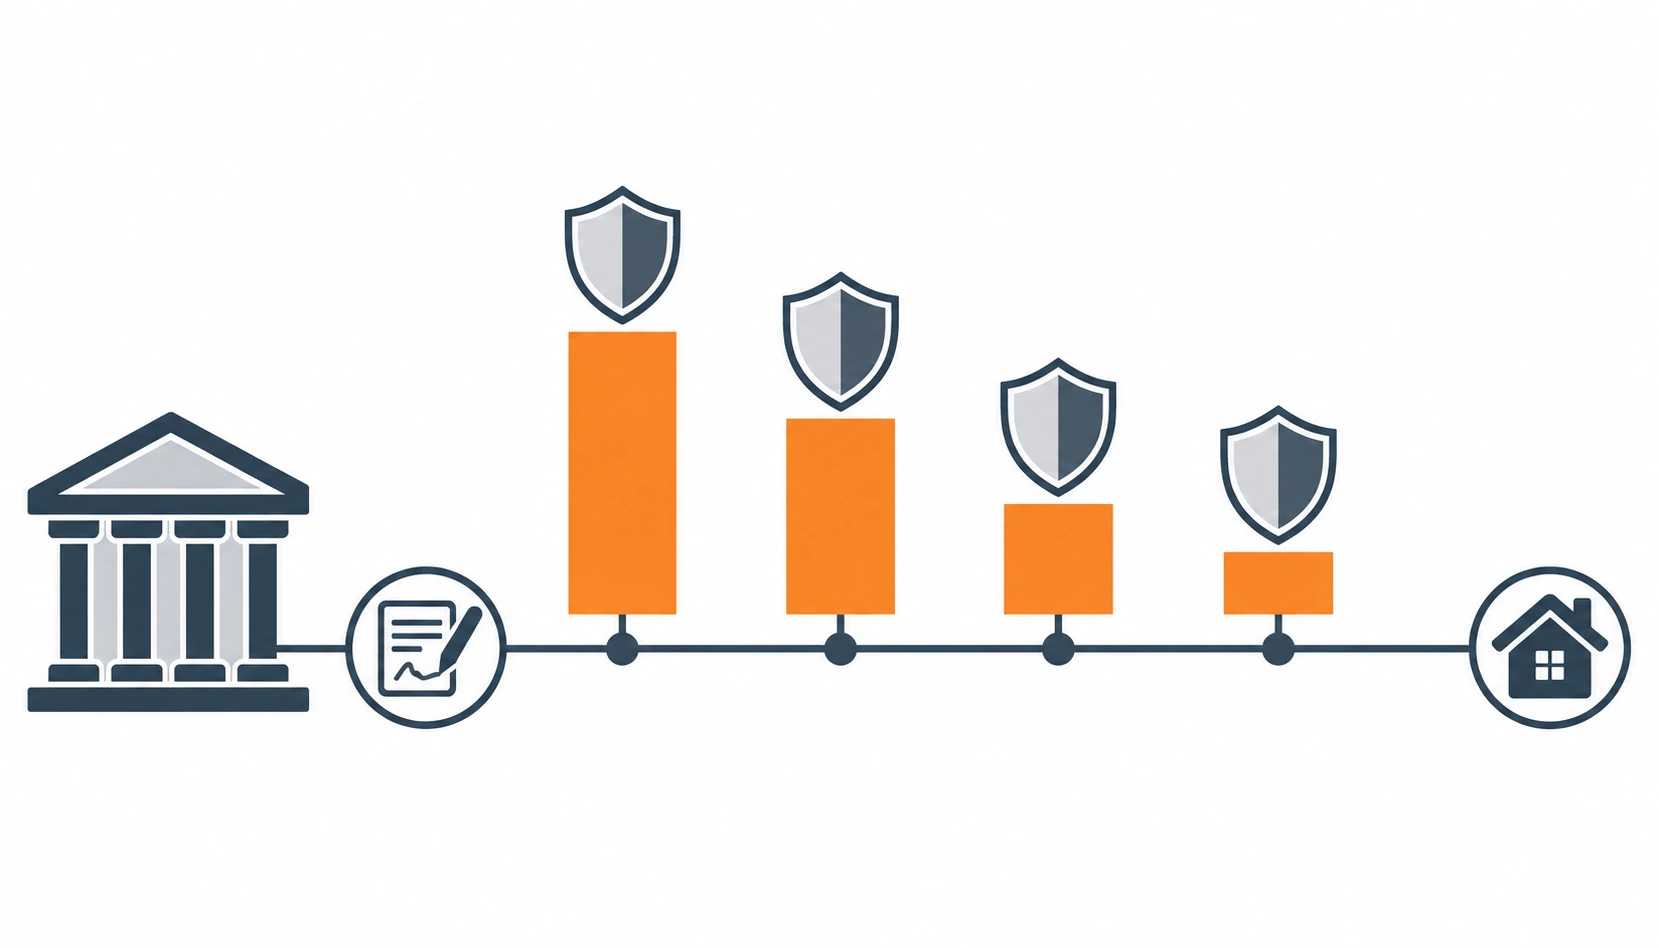
Quick Answer: A Central Asian cable contract usually carries a chain of bank guarantees: a bid security with the offer, a performance guarantee at signing, an advance payment guarantee if the purchaser finances mobilisation, and sometimes a warranty guarantee for the defect liability period. Each instrument shifts a different risk onto the supplier, and each one ties up bank capacity and cash while it lives. The wording decides everything: what triggers a call, when the instrument expires and who pays the bank’s cost of carrying it.
Introduction
Cable tenders in the region are won on price and secured on paper, and the securing paper is the guarantee chain. Purchasers use it because a cable order moves in phases: bid before production, contract before shipment, advance before drums. A guarantee answers the purchaser’s question at each phase, which is why the requirements arrive in the tender and the contract rather than in negotiation.
This page explains the chain for suppliers, distributors and EPC bid teams: what each instrument commits, how the wording changes the risk, and how the chain behaves in cash-flow terms across a long delivery. The full tender path sits in our Central Asian cable tender guide; this page stays with the security layer. Payment mechanics next to it are covered in our note on cable payment terms, and purchaser expectations across the region are collected in our Central Asian cable buying hub.
The Guarantee Chain Across the Contract Life
The chain follows the contract’s phases. The bid guarantee lives from submission to contract signature or bid expiry, and it compensates the purchaser if a winner refuses to sign. The performance guarantee takes over at signature and covers delivery and obligations. Where the purchaser pays an advance, an advance payment guarantee covers the money until it is earned back through deliveries, and a warranty guarantee can extend cover into the defect liability period.
Instruments hand over to each other, and the handovers are where claims and gaps live. A performance guarantee issued while the bid guarantee is still alive duplicates cover and costs twice; a performance guarantee that starts late leaves an uncovered window between signature and issuance,. Map the dates on one page before the bank is involved.
The chain also outlives the delivery. Warranty guarantees can run for years after the drums are energised, and they sit against retention money and the warranty terms themselves. The warranty layer’s interaction with the commercial terms is in our note on power cable warranty terms.
The Bid Guarantee: What It Commits
The bid security commits one thing: if the tender’s rules are broken in a named way, typically refusing to sign or to furnish the performance guarantee after winning, the purchaser may call the instrument. It is not a quality deposit and it does not cover delivery risk. The exposure is narrow, so the main cost is bank capacity rather than fees.
The wording to watch is the expiry and the return mechanics. A bid guarantee that expires at a fixed date can strand a bidder whose award is delayed; one that expires on signature works cleanly but has to name what happens if the tender is cancelled. Confirm in writing how and when the original is returned; guarantees never returned keep occupying bank limits.
Where a consortium or a distributor bids with a manufacturer behind it, the guarantee issuer matters to the purchaser as much as the existence of the instrument. A first-tier bank with regional presence reads differently from an issuer the tender commission cannot verify,
The Performance Guarantee: Scope and Wording
The performance guarantee covers the supplier’s obligations under the contract, and its wording decides how wide that cover reaches. The instruments purchasers prefer are on-demand: the bank pays on a written claim without the supplier’s consent or a court finding. Suppliers should price and manage that risk rather than pretend it away.
The scope definitions matter more than the percentage everyone argues about. Whether the guarantee covers delivery dates only, or documentation and acceptance too, changes what a dispute can touch. A guarantee that releases in part against each consignment or each milestone behaves very differently from one that stands at full value until final acceptance
Reduction clauses are the supplier’s best friend in this layer and easy to lose in negotiation without noticing. A guarantee that steps down as deliveries are accepted converts a long-lived full-value exposure into a declining one, and it aligns the bank’s instrument with the actual remaining risk. Ask for the schedule of reductions in the contract annexes, not in an email.
Advance Payment Guarantees and Working Capital
Where the contract provides an advance, the purchaser covers the exposure with an advance payment guarantee that reduces as the advance is earned back through deliveries. The instrument protects the money, not the schedule, and the reduction mechanics have to mirror the earning logic in the contract. Mismatched reduction schedules are a classic source of cash trapped in guarantees after the advance has already been worked off.
For a cable manufacturer the advance is working capital: copper is bought early in the delivery cycle, and the price of that copper is the largest moving part of the margin. How the purchase protects itself against the metals market sits in our notes on the copper basis lock, locking the copper price in a cable contract and copper price in cable procurement, and the guarantee structure should be read together with those mechanics.
Suppliers without deep credit lines sometimes bridge the advance stage with cash at sight terms instead: a higher payment share early, no guarantee, a weaker position on claims. What does not work is an advance structure the factory’s bank cannot issue at contract speed.
Conditional Versus On-Demand Instruments
A conditional guarantee pays only when the supplier’s breach is established, by agreement or by a finding. An on-demand guarantee pays on the beneficiary’s written demand, and the supplier’s remedy afterwards is a claim of abuse. Purchasers in infrastructure procurement insist on demand instruments; the conversation worth having is about scope, reduction and expiry.
The abuse-claim route exists and works, but it is slow and jurisdiction-dependent. The drafting before signature carries the value. Clear demand requirements in the instrument, named documents a claim must contain, and an expiry that cannot float indefinitely are the parts that make an on-demand guarantee livable for a supplier.
Expiry deserves its own negotiation. Purchasers ask for expiry at final acceptance plus a margin; open-ended instruments tied to “discharge of obligations” can live for years against a delivery that closed long ago. Where the contract has a defect liability period, the answer is usually a fixed expiry with a separate, smaller warranty guarantee if the purchaser genuinely needs extended cover,.
Which Bank, Which Jurisdiction
The tender or contract usually names where the guarantee must be issued: a local bank, a first-class international bank, or a local bank confirmed by an international one. Each structure has a cost and a speed. Local issuance satisfies the purchaser fastest and reads best in evaluation; international issuance protects the supplier’s control of the instrument but can need confirmation at a cost nobody prices until the second tender.
Cable suppliers exporting into the region typically run a standing arrangement with their own bank plus a correspondent in the destination country, and the arrangement is built across tenders, not improvised for one. The bank’s ability to issue in the exact format the tender prescribes, including any local-language text, is part of bid readiness; mismatches read as inexperience.
Where a local partner or agent fronts the bid, the guarantee question splits in two: whose bank issues, and whose balance sheet the instruments occupy. That question belongs in the representation decision, and the mechanics are compared in our note on building framework supply from a first RFQ.
Cash-Flow Mechanics for a Cable Manufacturer
Every guarantee in the chain occupies the supplier’s bank lines from issuance to release, and bank lines price that occupancy. A contract with long validity and phased deliveries can hold instruments against one project for a large share of available limits, which quietly caps how many projects the factory can run at once.
Time the chain against the production calendar. Copper is bought before the first drum ships, so the advance and its guarantee matter earliest; the performance guarantee’s full-value period should overlap the riskiest delivery months, not the quiet ones; and release points should be tied to acceptance documents the site actually issues. A delivery schedule and a release schedule that do not match are a cash trap drawn in legal language; the production planning behind the calendar is in our note on cable MOQ and lead time.
Track the chain like inventory. Each instrument has an issue date, a value, a reduction schedule and a release condition, and someone in the finance function owns the calendar. Guarantees past their usefulness cost fees for every day they live, and the released limit is the one that can bid on the next tender.
The Guarantee Set at a Glance
The table lines up the instruments in the chain, what each commits and where the negotiation usually lands.
| Instrument | What It Commits | Trigger | Lifetime | Where Negotiation Lands |
|---|---|---|---|---|
| Bid guarantee | Winner signs and posts the performance guarantee | Refusal to proceed after award | Submission to signature or expiry | Expiry date and written return mechanics |
| Performance guarantee | Full supply obligations of the contract | On-demand written claim | Signature to final acceptance | Scope, reduction schedule, fixed expiry |
| Advance payment guarantee | Repayment of the unearned advance | Contract termination before earning back | Advance receipt to earned-back point | Reduction mirroring the earning logic |
| Warranty guarantee | Obligations in the defect liability period | Unremedied defects in the period | Acceptance to end of defect period | Size versus retention money, fixed expiry |
| Retained retention money | Purchaser-held share of payments | Held against defects and closeout | Payment to release at closeout | Release against guarantee substitution |
Guarantee Terms to Freeze Before Signing
These are the terms to settle while the contract is still a draft, in the order the arguments usually arrive.
| Term to Freeze | How to Write It | What to Attach | Cost of Leaving It Open |
|---|---|---|---|
| Instrument types and timing | Chain table: which guarantee, issued when, released when | Issue-and-release calendar agreed in the annexes | Uncovered windows and duplicated cover |
| Performance scope | Named obligations covered, documentation and acceptance included or excluded explicitly | Draft instrument text annexed to the contract | A claim reaching far past the delivery itself |
| Reduction schedule | Value steps down against consignments or milestones accepted | Reduction table keyed to acceptance documents | Full-value exposure long after delivery |
| Demand requirements | Claim must state the breach and attach named documents | Specimen instrument agreed with the issuing bank | Any written demand paying without form |
| Expiry discipline | Fixed expiry dates, no floating "until discharged" wording | Expiry dates on the contract calendar | Instruments living for years against closed deliveries |
| Issuing bank | Issuer named or class defined, confirmation structure agreed | Bank's format library checked against tender text | Format mismatches discovered at submission or issuance |
| Fee and cost allocation | Who pays issuance, confirmation, amendment and cable costs | Cost schedule in the commercial annex | Fees surfacing as deductions from payments |
When a Guarantee Is Not the Answer
When the risk is performance, not payment. A guarantee compensates after a failure; it does not prevent one. Where the real risk is a schedule the factory cannot hold, the answer is a delivery plan with float and a copper basis that moves with the market.
When the counterparty risk sits elsewhere. Where the worry is the purchaser’s payment behaviour, the instruments that matter are the payment terms and the currency route, and a supplier posting heavy guarantees into a weak payment structure has bought insurance for the wrong side of the deal.
When the bank line is the scarce resource. A factory at the edge of its limits can bid fewer projects than its order book suggests. Sometimes the right move is a smaller guarantee package with earlier reductions.
When local law reshapes the instrument. Enforceability of demand guarantees and the treatment of foreign issuers vary across the region, so local counsel reviews before signature, not after a claim.
When the guarantee substitutes for the acceptance process. A purchaser who relies on the guarantee instead of running a clean acceptance sequence is storing a dispute. Insist on the inspection and acceptance steps in the contract; the instruments sit behind a working process, not in place of it.
RFQ Checklist
- Guarantee chain mapped per contract: type, value, trigger, lifetime, release
- Bid guarantee expiry matched to the tender’s award timeline, return in writing
- Performance scope written narrowly, documentation and acceptance named explicitly
- Reduction schedule keyed to acceptance documents, annexed to the contract
- Demand requirements fixed: stated breach plus named documents
- Fixed expiry dates on the contract calendar, no floating wording
- Issuing bank and confirmation structure agreed before submission
- Fee allocation written into the commercial annex
- Bank limit occupancy tracked as part of project capacity
- Warranty cover reconciled against retention money and warranty terms
Conclusion
The guarantee chain is the contract’s shadow balance sheet: it follows the same phases, and it consumes the supplier’s cash and credit in proportion to how loosely it is drafted. Suppliers who negotiate scope, reductions and expiries at draft stage run the same projects on visibly less bank capacity, and the difference compounds across a regional order book.
Kexingyu Cable Group (KXYE) structures guarantee packages around the delivery calendar, with reduction schedules that follow acceptance and expiries that end when the risk does. Send the contract draft and the destination country. A request for quotation is the fastest start, and the offer fields we work from are in our industrial cable RFQ checklist.