Middle East Power Meets Compute: Cable Opportunities in GCC Grids
Quick Answer: In the Gulf, grid buildout and computing boom are one story — the suppliers who read the GCC as one connected system win the corridor, not just the country.
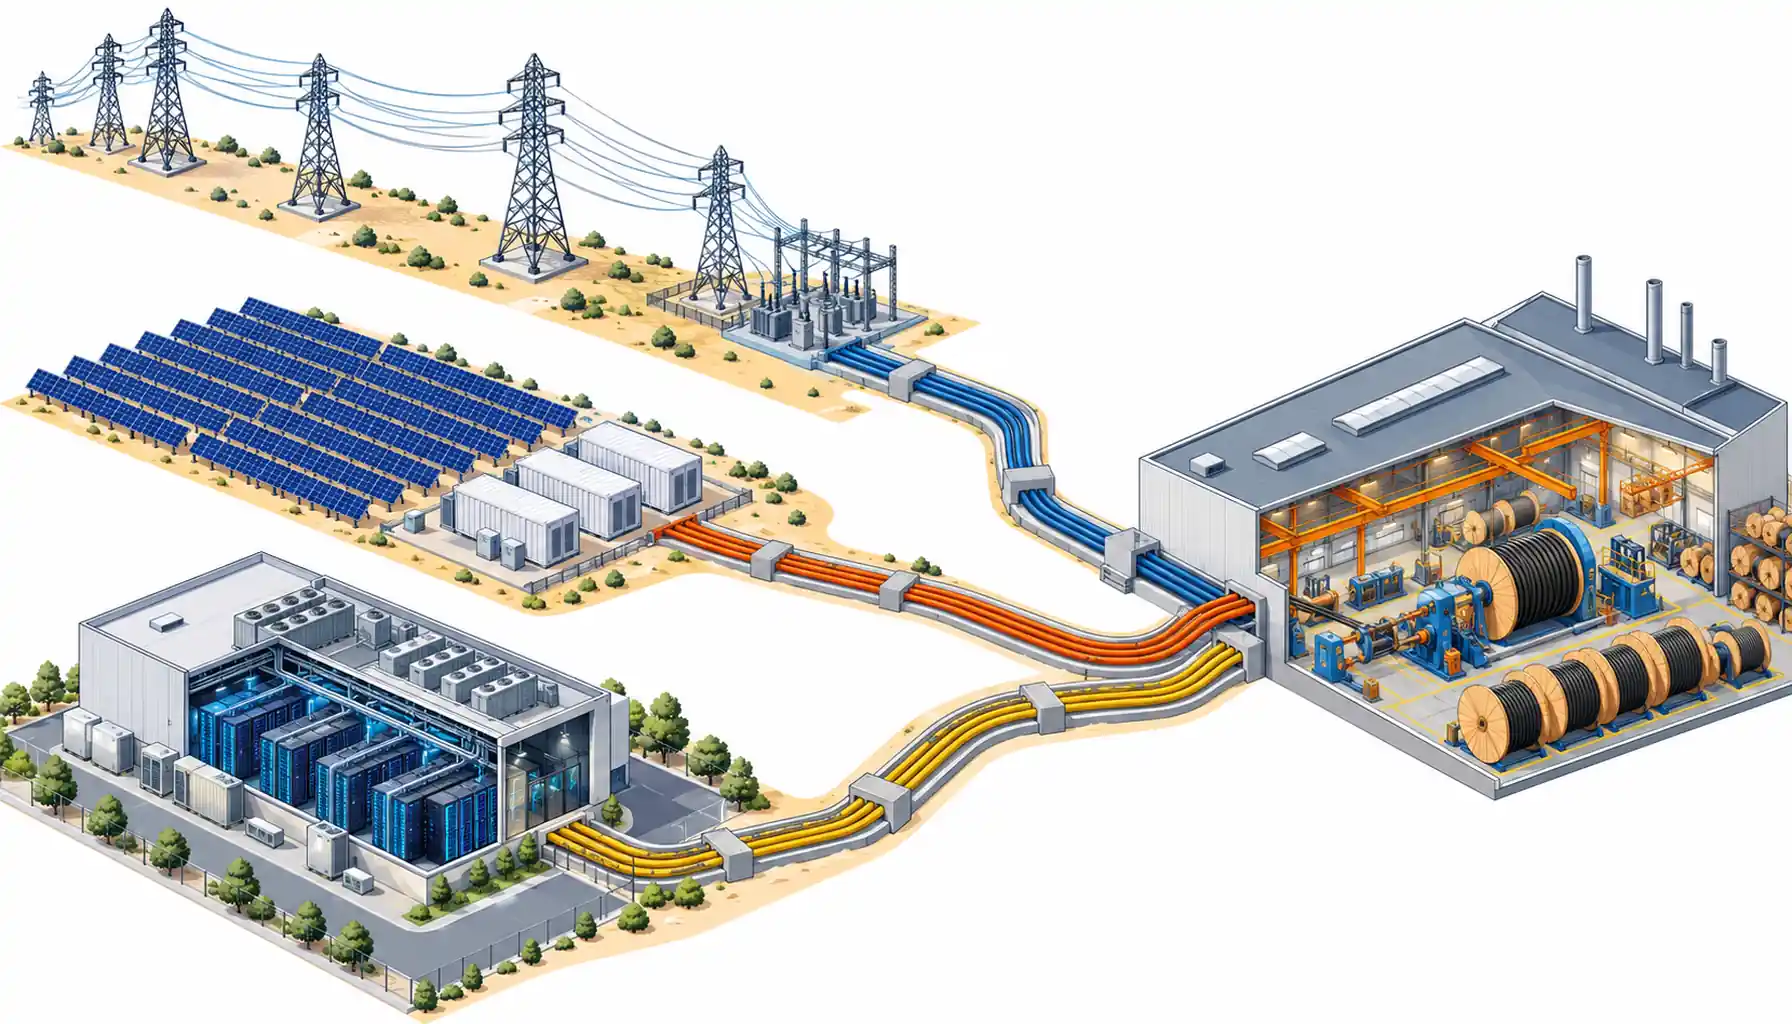
Step back from any single Gulf market and the pattern appears: the GCC is wiring itself into one system. A cross-border interconnector already links the national grids; generation is being added at gigawatt pace, much of it solar; storage is following the sun; and the data centers that justify the computing half of the story are landing exactly where the power is most dependable. For cable suppliers, this is the market-level view the country guides cannot give: a region whose demand compounds because its power and its compute are being built together. This guide maps the system, the cable bill it generates, and the supply posture that captures it.
Introduction
The regional sourcing landscape is mapped in Middle East power equipment sourcing; this article zooms out to the system level. The Gulf’s electricity story — generation expansion, grid strengthening, cross-border trade — follows the equipment families of utility grid expansion equipment, and its computing story lands on the demand curve of data center power demand growth. The GCC’s distinctive move is fusing the two: interconnection lets countries trade power and firm their grids, dependable grids make hyperscale campuses bankable, and hyperscale campuses justify the next round of generation. Each layer of the fusion buys cable — and the layers multiply each other.
The System View: Three Demand Engines, One Cable Bill
Engine one is the grid itself: transmission backbones, substation programs and the interconnection infrastructure that ties national systems together — MV cable, substation wiring and the accessories program around them. Engine two is the energy transition layered onto the grid: utility-scale solar and the storage that firms it, where the DC and AC sides both buy cable and the integration logic of solar-plus-storage systems decides how the two sides meet. Battery-side cabling repeats wherever storage firms a digital load. Engine three is compute: the hyperscale and enterprise halls of Saudi, the UAE, Qatar and beyond, each carrying the standard data-hall bill. The system point is the overlap: the same factories, the same MV and LV families, the same documentation discipline serve all three engines. A supplier strong in one engine inherits the other two.
| Demand Engine | Leading Cable Families | System Effect |
|---|---|---|
| Grid expansion and interconnection | MV XLPE feeder cable, substation wiring, accessories | Firms the grid that makes compute bankable |
| Solar and storage | DC and AC solar cable, battery-side cabling | Adds generation where the digital load lands |
| Data centers | MV intake, LV distribution, UPS strings, LSZH halls | Justifies the next round of generation |
| Corridor overlap | Shared families across all three engines | One qualified supplier serves the whole system |
Reading the Corridor: Where the Demand Concentrates
The system view also predicts geography. Compute lands where power is dependable, so the corridor’s cable demand concentrates along the axis the grid buildout strengthens first — the Kingdom’s load centers and giga-projects, the UAE’s free-zone clusters, Qatar’s compact national program — with the interconnector making the boundaries softer for power and, eventually, for the suppliers who follow it. Solar and storage follow the same map for a different reason: the best solar resource and the cheapest land sit beside the transmission paths, so the energy-transition bill lands on the same routes as the compute bill. For a supplier, the practical reading is a route map: qualify at the national gates along the axis, hold evidence that transfers between them, and watch the interconnection announcements. Every strengthening of the grid firms the next campus site, and the cable orders follow the substations, not the headlines. The corridor doesn’t distribute demand evenly; it concentrates it along the power. Reading the power map is reading the sales map.
What the Corridor Rewards
The Gulf corridor rewards two postures that weaker markets do not. The first is capacity honesty: the region’s programs are national in size and calendar-locked, and the equipment families around cable — switchgear, transformers — already run on stretched schedules tracked in transformer lead-time shortage planning. Cable quotes that ignore the family calendar break campuses, and buyers know it. The second is systems selling: buyers procuring grid, solar and compute programs in parallel increasingly prefer suppliers who coordinate the families on one timeline — the integrated logic of one-stop power equipment sourcing — because a single accountable calendar beats three mismatched ones. The recurring failure catalog of international power equipment sourcing mistakes applies at corridor scale. The costliest error is treating six sophisticated markets as one undifferentiated region, because each national gate still demands its own file.
| Stage | Action | Classic Trap |
|---|---|---|
| Market mapping | National gates, standards and buyers mapped per country | Treating the GCC as one undifferentiated region |
| Qualification | Evidence files assembled per national gate, current and reused | One generic file across six different regulators |
| Bidding | Family calendar — cable, switchgear, transformers — quoted honestly | Cable lead times quoted without the equipment context |
| Delivery | Batch identity and schedules reconciled per national program | Corridor-level promises without country-level proof |
| Compounding | Credential carried across engines: grid to solar to compute | Serving one engine and ignoring the overlap |
When a Regional Story Is Not a Regional Shortcut
Two cautions frame the opportunity. A connected grid doesn’t mean connected paperwork: interconnection trades power between countries, not conformity files, and each national gate — utility standards, certification regimes, institutional buyers — still demands its own evidence in its own format. And a compounding demand story is not a demand guarantee: the same fusion that grows the bill concentrates it. Programs land where power is dependable, and the suppliers who follow the power map, not the press releases, are the ones whose calendars hold. Read the corridor as a system, serve it as six disciplined markets, and the compounding works in the supplier’s favor exactly as it does in the region’s.
RFQ Checklist: GCC Lines for the RFQ
Put the market’s questions in writing:
- National-gate evidence files listed per target country, current and reusable
- Constructions mapped to each market’s utility and consultant standards
- Family calendar — cable, switchgear, transformers — quoted as one schedule
- Solar and storage cable families offered alongside the grid and hall bill
- Batch identity and marking commitments per national program
- Heat-derated parameters stated for Gulf site conditions
- Corridor framework terms that reuse qualification across borders
Conclusion
The GCC is the clearest example anywhere of power and compute being built as one system: interconnection, generation, storage and data halls pulling the same cable bill in the same decade. The market rewards suppliers who read the system, who map the national gates inside the regional corridor, quote the family calendar honestly, and let each engine’s qualification open the next. The cable volume compounds because the system does.
Kexingyu Cable Group (KXYE) serves the Gulf as the system it is: grid, solar, storage and data hall families under one calendar, national-gate evidence files maintained per country, and schedules quoted honestly at corridor scale — cable supply for a region that wires its power and its compute together. The compounding works only for suppliers who keep the country files current behind the regional story, because the corridor opens doors, but the national gate still decides who walks through.